
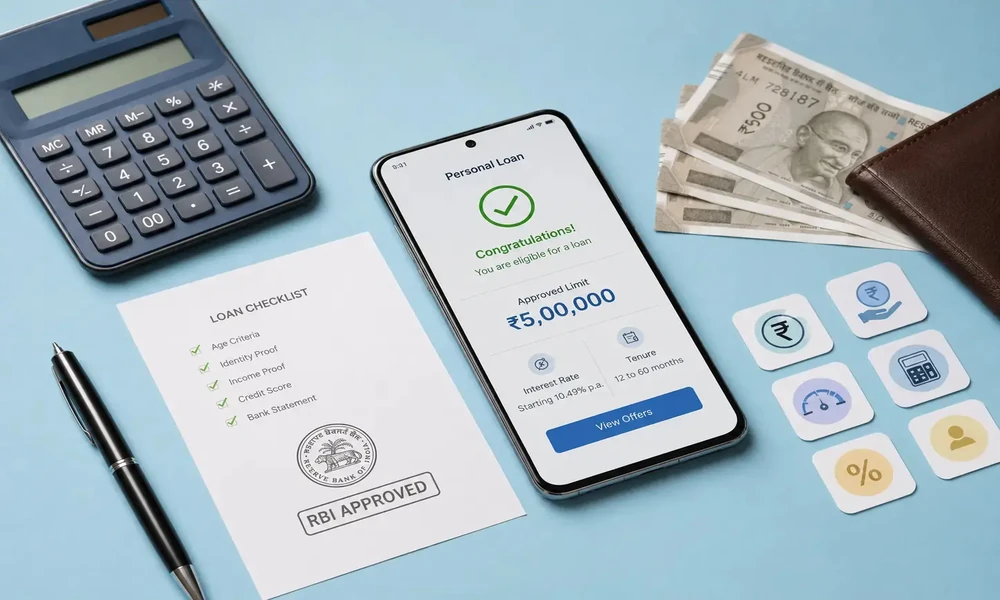
Applying for a personal loan no longer necessarily involves multiple visits or lengthy paperwork. Many lenders now provide digital application processes through mobile platforms, allowing borrowers to submit information, complete verification and review loan terms online.
But a convenient application process does not mean every loan offer will suit every borrower. Before using loan apps, it is important to understand the amount required, check eligibility, compare the complete cost and make sure the repayment fits comfortably within the monthly budget.
1. Start With a Clear Reason for Borrowing
It’s crucial to identify why the loan is needed. A clear purpose makes it easier to decide whether the funds from the loan are necessary.
For example, someone may need ₹75,000 for a planned home expense but have ₹25,000 available in savings. The actual funding gap may therefore be ₹50,000 rather than ₹75,000.
Calculate what you need and deduct it from the amount you have in order to keep the loan amount low.
2. Check Your Monthly Repayment Capacity
The loan amount should not be decided independently of the monthly budget. An EMI continues after the immediate expense has been paid, so it needs to fit alongside existing financial commitments.
Before applying through a personal loanapp in India, calculate your monthly income and subtract essential expenses, existing EMIs and regular financial commitments. The amount left over gives a better indication of whether a new EMI is manageable.
3. Check the Lender Behind the App
An app is not necessarily the entity providing the loan. It may provide the digital interface while the credit is offered by a bank or NBFC.
Before submitting an application, identify the actual lender and verify the relevant details through reliable sources. Do not select a lending platform solely because it appears prominently in an app store or search result.
Understanding who is providing the loan also makes it easier to find the applicable loan agreement, customer support and grievance information.
4. Review Eligibility Requirements
Different lenders can levy different eligibility requirements. These may include factors such as age, income, employment or business profile, credit history and existing financial obligations.
Checking the basic eligibility requirements before applying can help you avoid submitting unnecessary applications.
It is also important to provide accurate information. Differences between the information entered during an application and the documents or records used for verification can delay the process or affect the lender’s assessment.
5. Keep the Required Information Ready
One advantage of an online personal loan app is that much of the application can be completed digitally. However, borrowers may still need to provide information or documents for identity, income and other verification requirements, depending on the lender.
Commonly requested information may include: PAN, address information, and bank account details.
Keep the information accurate and up to date. Avoid submitting documents through unofficial links or channels that cannot be verified.
6. Compare the Full Cost of the Loan
A personal loan should not be compared only on the basis of the advertised interest rate or EMI.
Before accepting an offer, check the:
- Interest rate
- Annual Percentage Rate (APR), where applicable
- Processing fee
- Other applicable charges
- EMI
- Repayment tenure
- Total repayment amount
- Late payment charges
- Prepayment or foreclosure terms, where applicable
For example, two loans may offer the same ₹1 lakh amount but have different fees and repayment periods. Looking at the total repayment gives a clearer picture of which terms fit the borrower’s financial situation.
7. Read the Loan Agreement Before Accepting
Once the application is approved, do not rush through the final acceptance simply because the funds are needed.
An easy personal loan app can make the application process straightforward, but the convenience of the interface should not replace careful review of the loan agreement.
Check the sanctioned amount, disbursal amount, interest, applicable charges, EMI, tenure and repayment conditions. If any part of the agreement is unclear, seek clarification before accepting the loan.
8. Avoid Applying to Multiple Lenders Without a Reason
If an application is rejected or does not meet expectations, it can be tempting to immediately apply through several other platforms. However, repeatedly seeking credit within a short period may not be the best approach.
Instead, understand why the first application did not work and reassess the amount required, eligibility and repayment capacity. Compare available options before submitting another application.
The goal should be to find a loan that fits the financial requirement rather than collecting multiple offers that could create unnecessary commitments.
9. Have a Repayment Plan Before the Money Arrives
The loan should have a repayment plan from the moment it is accepted.
Consider where the EMI will come from each month and whether income is expected to remain stable throughout the tenure. If the loan is being used for a one-time expense, avoid assuming that another loan will be available later to manage the repayment.
A personal loan becomes easier to manage when the borrower knows the amount needed, understands the complete cost and has enough monthly surplus to accommodate the EMI.
A Quick Pre-Application Checklist
Before submitting a personal loan application, check these points:
| Check | Question to ask |
|---|---|
| Purpose | Do I have a clear reason for borrowing? |
| Amount | Am I borrowing only what I actually need? |
| Affordability | Can my monthly budget accommodate the EMI? |
| Lender | Do I know which entity is providing the loan? |
| Eligibility | Do I meet the stated requirements? |
| Cost | Have I checked the interest, fees and total repayment? |
| Terms | Have I read the loan agreement? |
| Security | Am I using an official and verifiable application channel? |
| Repayment | Do I have a clear plan for every EMI? |
Make the Application Process Work for Your Budget
A digital application can make borrowing more convenient, but convenience should not be the deciding factor. Start with the actual financial requirement, assess your repayment capacity, verify the lender and compare the complete cost of the loan. Once the application is approved, read the agreement carefully and plan the EMI before using the funds.
